Clinical Decision Support Systems Market Trends, Demand & Industry Outlook
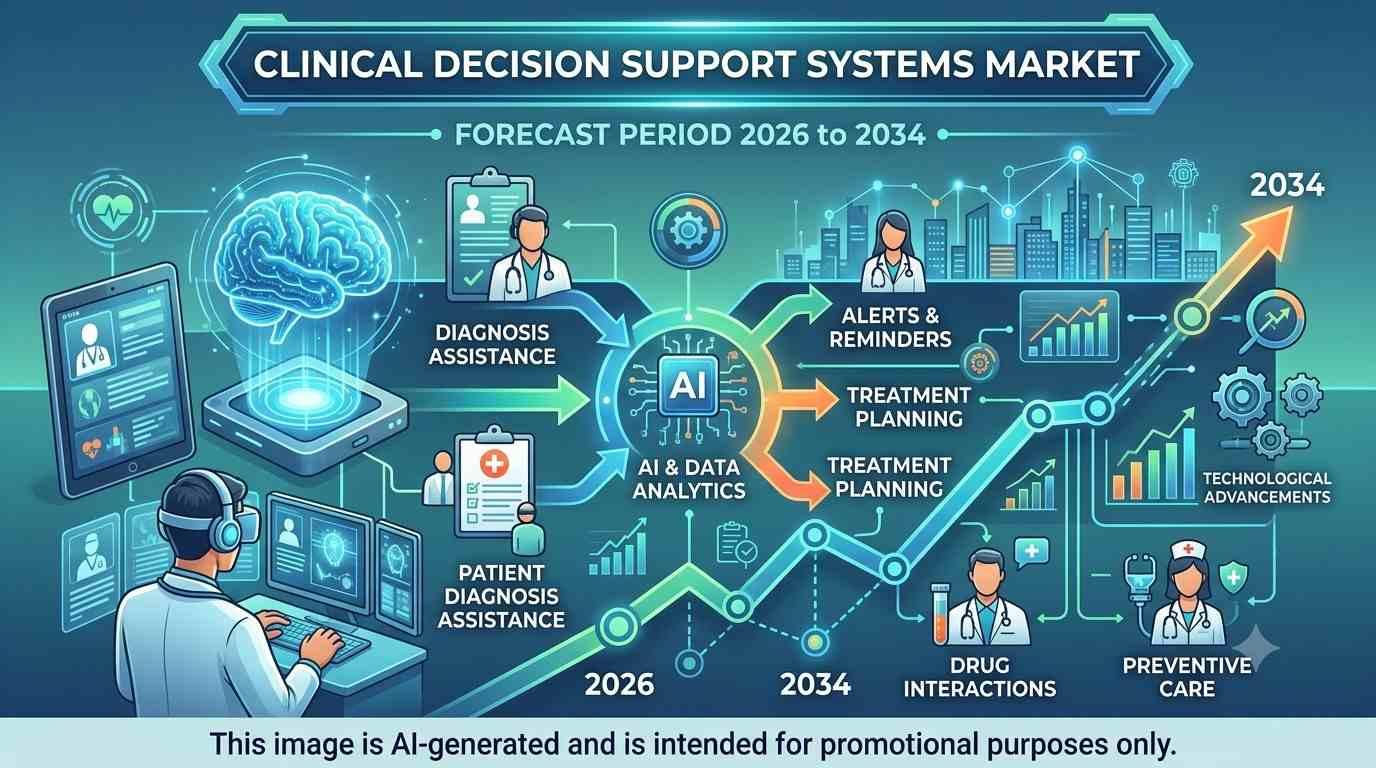
The Clinical Decision Support Systems Market is expanding as healthcare providers, hospital networks, and digital health developers shift toward evidence-based platforms that reduce medical errors, optimize clinical workflows, and improve overall patient outcomes. Growth is supported by government digital health initiatives, widespread adoption of Electronic Health Records (EHR), integration of artificial intelligence (AI), and investments in cloud infrastructure.
The global clinical decision support systems market size is projected to reach US$ 16.84 billion by 2034 from US$ 6.52 billion in 2025. The market is anticipated to register a CAGR of 11.12% during the forecast period 2026-2034.
What is driving the market?
Regulatory compliance, the need to reduce preventable medical errors, and the rising complexity of patient care are the principal growth drivers. Healthcare providers are increasingly required to adhere to strict quality-of-care standards, minimize adverse drug events, and streamline decision-making in high-pressure environments. Hospitals, ambulatory care centers, and specialty clinics are seeking solutions that deliver real-time, evidence-based guidance directly at the point of care without creating administrative burnout.
The transition is moving beyond static, rule-based systems toward dynamic, AI-driven models. Software vendors are investing in machine learning algorithms, natural language processing (NLP), predictive analytics, and seamless EHR/CPOE integration. System interoperability, data privacy regulations, high implementation costs, and clinician alert fatigue remain important constraints.
Which region leads?
North America leads the market, accounting for an estimated 43%–45% share in 2025. Growth is driven by advanced healthcare IT infrastructure, high EHR adoption rates, government incentives (such as federal HHS updates), and a strong emphasis on clinical safety. The United States holds the largest single market share within the region.
Asia Pacific is the fastest-growing region, with a projected CAGR of 12.5%–13.8%. Growth is supported by expanding healthcare infrastructure, digital health transformations, rising chronic disease burdens, and hospital modernizations. China and India present significant opportunities as expanding hospital networks adopt electronic health record frameworks and AI-based triage and diagnostic tools.
Which segment leads?
Standalone CDSS is the leading product segment by historic installation base, representing an estimated 30%–31% of revenue in 2025 due to low initial cost and simple implementation. However, Integrated EHR/CPOE systems are accelerating rapidly as healthcare facilities prioritize unified clinician workflows.
By application, Drug Allergy Alerts leads with an estimated 25%–26% market share, driven by the critical need to prevent adverse drug reactions (ADRs) during prescription workflows. By delivery mode, On-Premise platforms led with over 41% share in 2025 due to legacy hospital systems, but Cloud-Based CDSS is identified as the highest-growth delivery segment due to scalability, remote accessibility, and lower total cost of ownership.
Which companies are prominent?
The report identifies Epic Systems Corporation, Oracle Corporation (Cerner), McKesson Corporation, Koninklijke Philips N.V., Wolters Kluwer, Siemens Healthineers, Elsevier, GE HealthCare, Athenahealth, and MEDITECH as prominent market participants.
These companies compete across clinical content databases, AI predictive modeling, EHR platform integrations, point-of-care mobile applications, and clinical workflow tools. Strategic differentiation increasingly depends on diagnostic accuracy, reduction of false-positive alerts, interoperability standards, real-time analytics, and data security compliance. The list reflects the report's competitive landscape rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from basic record-keeping support toward generative AI-enhanced, predictive clinical insights. CDSS specifications increasingly mandate interoperability standards, automated clinical pathway alignment, real-time risk stratification, and mobile accessibility for care teams. Modern regulatory frameworks and health agency policies are placing stricter emphasis on algorithmic transparency, bias reduction, and validated medical evidence behind AI-generated recommendations.
Healthcare providers are accelerating the deployment of cloud-native platforms, real-time alert filters to combat alert fatigue, and specialized tools for oncology, cardiology, and sepsis detection. Vendor selection is heavily tied to seamless API integration into existing clinical environments rather than standalone software functionality.
What are the major investment opportunities?
The strongest opportunities lie in AI and machine learning integration, cloud migration, specialized diagnostic algorithms, and interoperability tools. Investment in natural language processing (NLP) to structure unstructured clinical notes, predictive risk modeling for ICU settings, and automated clinical trial matching can significantly enhance system utility.
Additional opportunities include specialty-specific CDSS (e.g., precision oncology, rare disease diagnostics), remote patient monitoring (RPM) integration, and ambulatory care platforms. Subscription-based Software-as-a-Service (SaaS) delivery models offer recurring revenue streams as smaller clinics and community hospitals digitize their care workflows.
Asia Pacific and emerging economies offer attractive market entry potential due to rapid healthcare modernization and government-backed digital initiatives. Investors should prioritize solutions that balance clinical accuracy, fast deployment, user-friendly UI to avoid burnout, and strict alignment with global health data privacy regulations.
The Insight Partners provides comprehensive syndicated and tailored market research services in the healthcare, technology, and industrial domains. Renowned for delivering strategic intelligence and practical insights, the firm empowers businesses to remain competitive in ever-evolving global markets.
• Email: sales@theinsightpartners.com
• Website: theinsightpartners.com
• Phone: +1-646-491-9876
 Spanish
 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek